

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
Higher oil prices bolster Fed rate hike bets as gold losses deepen
- $4,100 comes into view for Gold as higher energy costs sustain inflation worries.
- Expectations of a further Fed rate increase by December continue to weigh on bullion.
- Trading beneath key daily SMAs leaves XAU/USD with a bearish broader technical outlook.
Gold (XAU/USD) trades near $4,123 at the time of writing. The metal is down 0.42% on Tuesday, heading for a third consecutive daily decline. Higher Oil prices associated with Middle East tensions are skewing global inflation risks upwards, strengthening expectations for interest rates to stay higher for longer.
Above $100, West Texas Intermediate (WTI) Oil has reached its highest level in more than a month. Houthi attacks on Saudi energy infrastructure, alongside more frequent attacks on vessels in the Strait of Hormuz, are intensifying fears of supply disruption.
Since the war began in late February, high energy costs have been a major driver of inflation pressure. This has led major central banks to increase interest rates this year, with markets remaining alert to additional tightening.
Both September inflation reports in the United States, the Consumer Price Index (CPI) and Producer Price Index (PPI), exceeded expectations. The readings reinforced expectations that the Federal Reserve (Fed) could raise rates again before year-end in its effort to return inflation towards the 2% target.
Following recent declines, the US Dollar (USD) and US Treasury yields are finding some support from these hawkish expectations. As borrowing costs rise, interest-bearing assets become more appealing relative to non-yielding Gold. A firmer US Dollar also raises the metal’s cost for buyers using other currencies.
At around 101.88, the US Dollar Index (DXY) is 0.10% lower on the day, though still above last week’s 101.58 low. The index measures the Greenback against a basket of six major currencies. The benchmark 10-year US Treasury yield, meanwhile, has recovered to near 5.13% from last week’s low of 5.03%.
For the October 27–28 meeting, however, traders broadly anticipate no change in Fed interest rates. Policymakers appear reluctant to make consecutive increases after September’s 25-basis-point rise. According to the CME FedWatch Tool, markets assign a 15% probability to a hike this month, compared with an 89% probability of an increase in December.
With few US economic releases ahead, shifts in Oil prices, the US Dollar and Treasury yields leave Gold exposed. Expectations of a hawkish Fed remain a substantial headwind.
Technical analysis: $4,100–$4,200 range holds as XAU/USD stays below key daily SMAs
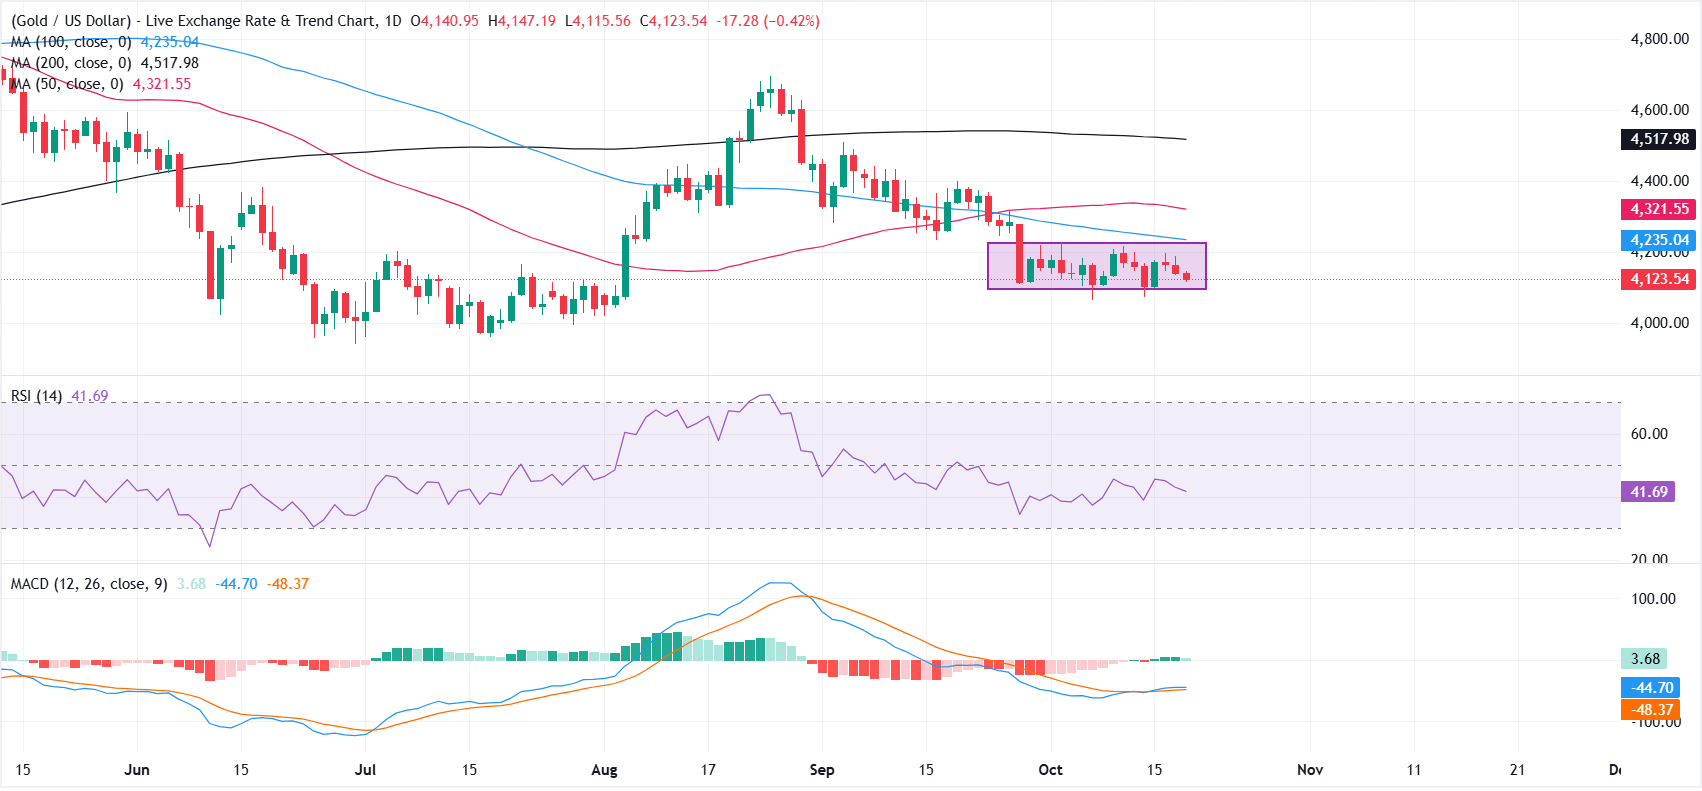
Since the month began, XAU/USD has largely traded between $4,100 and $4,200. The daily chart nevertheless retains a sequence of lower highs and lower lows following the late-August peak near $4,700.
Despite some recovery in momentum, the metal remains constrained beneath its 50-day, 100-day and 200-day Simple Moving Averages (SMAs). The Relative Strength Index (RSI) is in the low-40s, while the Moving Average Convergence Divergence (MACD) has turned positive above the zero line.
The first upside hurdle is the psychological $4,200 level. Beyond it, resistance stands at the 100-day SMA of $4,235 and the 50-day SMA of $4,321. A more substantial rebound would encounter the horizontal barrier at $4,400 before reaching the 200-day SMA at $4,517. Conversely, a sustained breach of $4,100 could clear a path towards the $4,000-$3,950 support zone.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Gold: Key Questions Answered
Widely used to preserve value and facilitate exchange, Gold has held an important place throughout human history. Today, its appeal extends beyond its lustre and use in jewellery. Investors widely regard the precious metal as a safe-haven asset, or an attractive investment during periods of turbulence. Because it depends on no particular issuer or government, Gold is also commonly viewed as a hedge against inflation and currency depreciation.
The largest holders of Gold are central banks. To underpin their currencies during turbulent periods, they typically diversify reserves and purchase Gold, bolstering perceptions of economic and currency strength. Substantial Gold reserves can strengthen confidence in a country’s solvency. World Gold Council data show that central banks increased their reserves by 1,136 tonnes in 2022, with the purchases valued at around $70 billion. That was the largest annual purchase on record. Emerging-economy central banks, including those in China, India and Turkey, are rapidly expanding their Gold holdings.
The US Dollar and US Treasuries, both important reserve and safe-haven assets, have an inverse correlation with Gold. A weaker Dollar typically supports the metal, allowing investors and central banks to diversify holdings during unsettled periods. Risk assets also tend to move in the opposite direction to Gold. Stock-market gains usually put pressure on the metal’s price, whereas selling in riskier markets generally supports it.
Many factors influence Gold prices. Its safe-haven role means geopolitical instability or concerns over a severe recession can trigger rapid gains. Lower interest rates generally benefit Gold because it offers no yield, while higher borrowing costs usually weigh on the metal. Nevertheless, the behaviour of the US Dollar (USD) drives most price movements, as Gold is quoted in dollars (XAU/USD). Dollar strength tends to restrain Gold prices; Dollar weakness is more likely to lift them.
POPULAR ARTICLES
10.7015 limits Australian Dollar upside against US Dollar – UOB2UK jobs data bolsters BoE hike bets, lifting British Pound against Euro318.50K: US ADP Employment Change 4-week average declines4British Pound: GBP rises on rate hike bets, but further gains look limited - BBH5$1.30 breached: Ripple Price Forecast as XRP sellers strengthen their grip6Hungarian Forint: Fiscal outlook clouded by crowded positioning - ING70.8270 rejection puts key support at 0.8225 at risk: USD/CHF Price Forecast8Higher oil prices bolster Fed rate hike bets as gold losses deepen9US Dollar: Further losses possible if equities weaken, says TD Securities
LIVE QUOTES


ALL ABOUT GOLD & PRECIOUS METALS
Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us












The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: [email protected]
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: [email protected]
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: [email protected]
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: [email protected]
Copyright © TMGM. All rights reserved