

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
6.3% rise in producer prices versus just 3.7% in consumer prices: chart reveals who absorbs the gap
6.3% was the annual rise in the Producer Price Index to September. Consumer prices increased 3.7%, leaving the widest gap since 2022. Energy and technology companies within the S&P 500 capture the difference; the other sectors bear the cost. Shoppers face their turn in 2027.
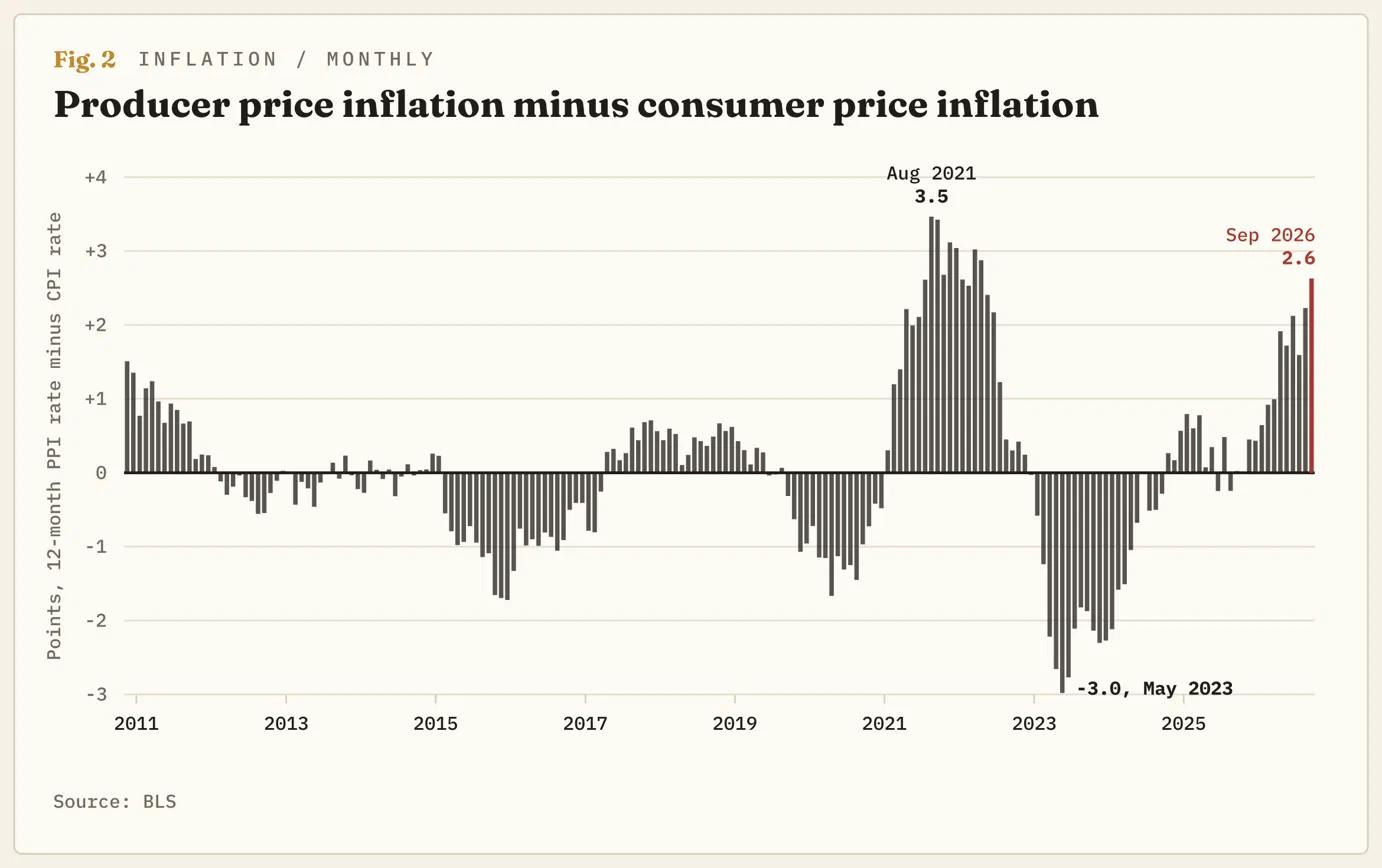
6.3% was September's annual increase in the Producer Price Index (PPI). That was the strongest reading since December 2022. Published by the Bureau of Labor Statistics (BLS), the PPI tracks the prices US businesses receive for their sales. The agency's other monthly inflation measure, the Consumer Price Index (CPI), tracks household spending prices and rose 3.7%. September's divergence left a 2.6-point gap, the eighth largest in the 16 years since the PPI adopted its current format. All seven larger gaps occurred between August 2021 and April 2022.
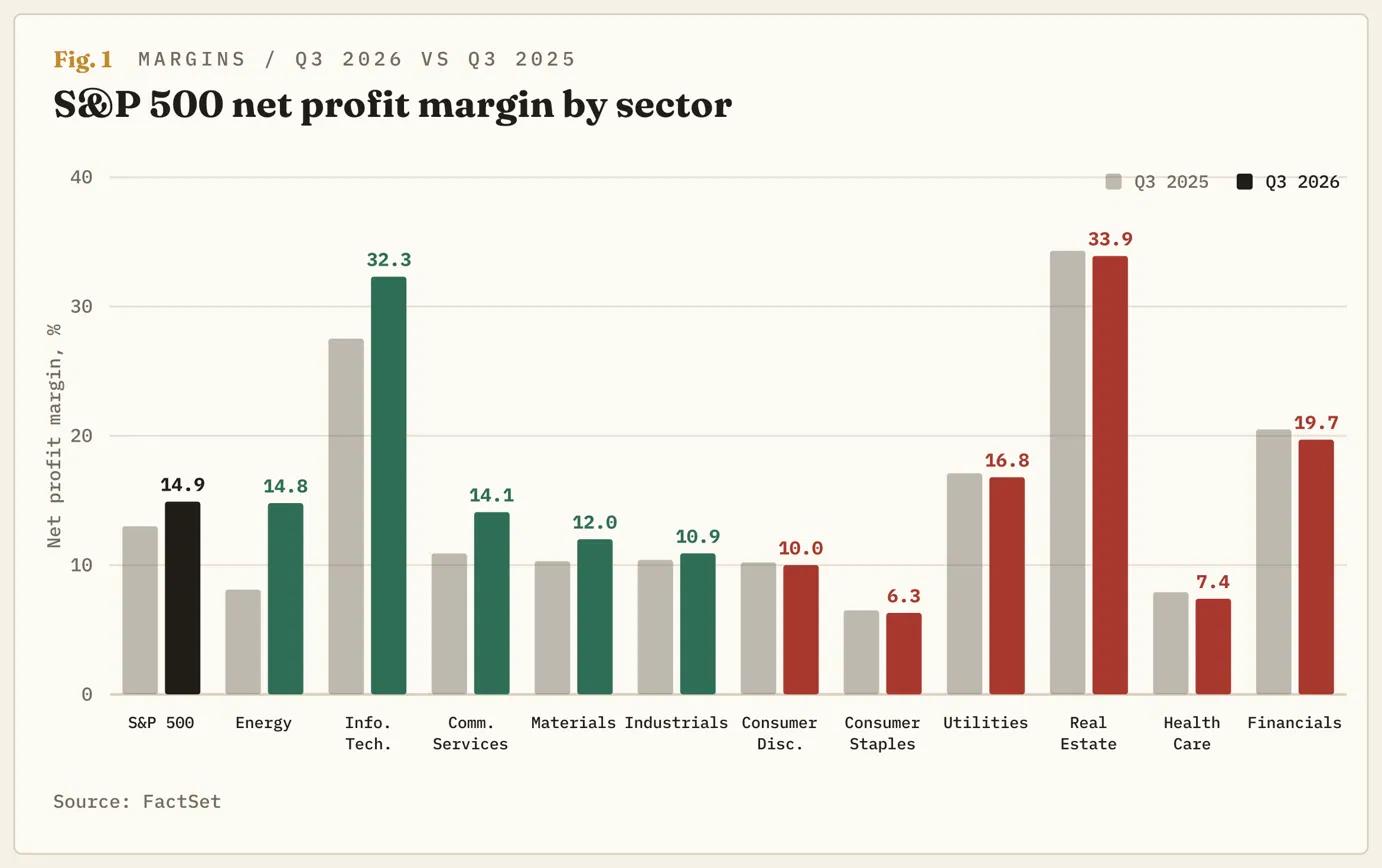
About 2% below its October 6 record, the S&P 500 also has near-record profitability. FactSet's figures, combining reported results and estimates, put this quarter's profit at 14.9 cents per dollar of sales. That is the second-highest margin in its data going back to 2009. These readings can coexist because the index holds businesses receiving the 6.3% increase alongside those paying it. This week's results have begun to reveal which companies sit on each side.
Two Sectors Drive the Average
Different index weightings explain some of the divergence. Housing accounts for a third of the CPI but is absent from the PPI, while energy producer prices jumped 10.8% in September alone. Beyond that arithmetic, money is shifting from buyers of fuel, resin and freight to their suppliers. Both sides of those transactions are represented in the S&P 500.
At 14.8%, the energy sector's margin compares with 8.1% a year earlier, according to FactSet. Quarterly oil prices averaged $85.68 per barrel against $64.97 previously, while earnings climbed 127.6%. Information Technology margins expanded from 27.5% to 32.3%. Yet six of the eleven sectors posted year-on-year margin declines, among them Consumer Staples, Health Care and Consumer Discretionary. Almost two points of margin expansion across the index masks the fact that 48% of its companies now make less profit per sales dollar than a year earlier. The record 17% margin in the June quarter included paper gains on Anthropic stakes held by Alphabet (GOOG, GOOGL) and Amazon (AMZN). Consecutive quarters have therefore delivered the two highest margins since 2009: one supported by an AI company's valuation, the other by a tanker war.
3.5-Point Gap Last Time: Shoppers Paid, Margins Still Fell
For seven months across 2021 and 2022, the gap exceeded today's level. Its peak was 3.5 points in August 2021. As that peak approached, the index's margin reached a record 13.1% in the June 2021 quarter. Six quarters on, it had dropped to 11.2%, its lowest since 2020. Eight of the eleven sectors recorded year-on-year margin declines in the December 2022 quarter. Energy went the other way, rising from 9.3% to 12.9%. It is repeating that performance now, but from a higher starting point.
Consumer prices rose to close the gap from below. As businesses passed on costs, CPI inflation reached 9% in June 2022, but margins contracted nonetheless. Producer inflation stayed at 10% or above for eight months; shelf prices caught up only after that run ended. From its January 2022 peak to its October 2022 trough, the S&P 500 lost about 25%. The Federal Reserve marks the difference this time (Fed). During that decline, it lifted rates from zero to above 4%. It enters the current episode near 4%, following a rate increase on September 16.
$1.4 Billion Cost Bill: Soap, Cigarettes and Pickups
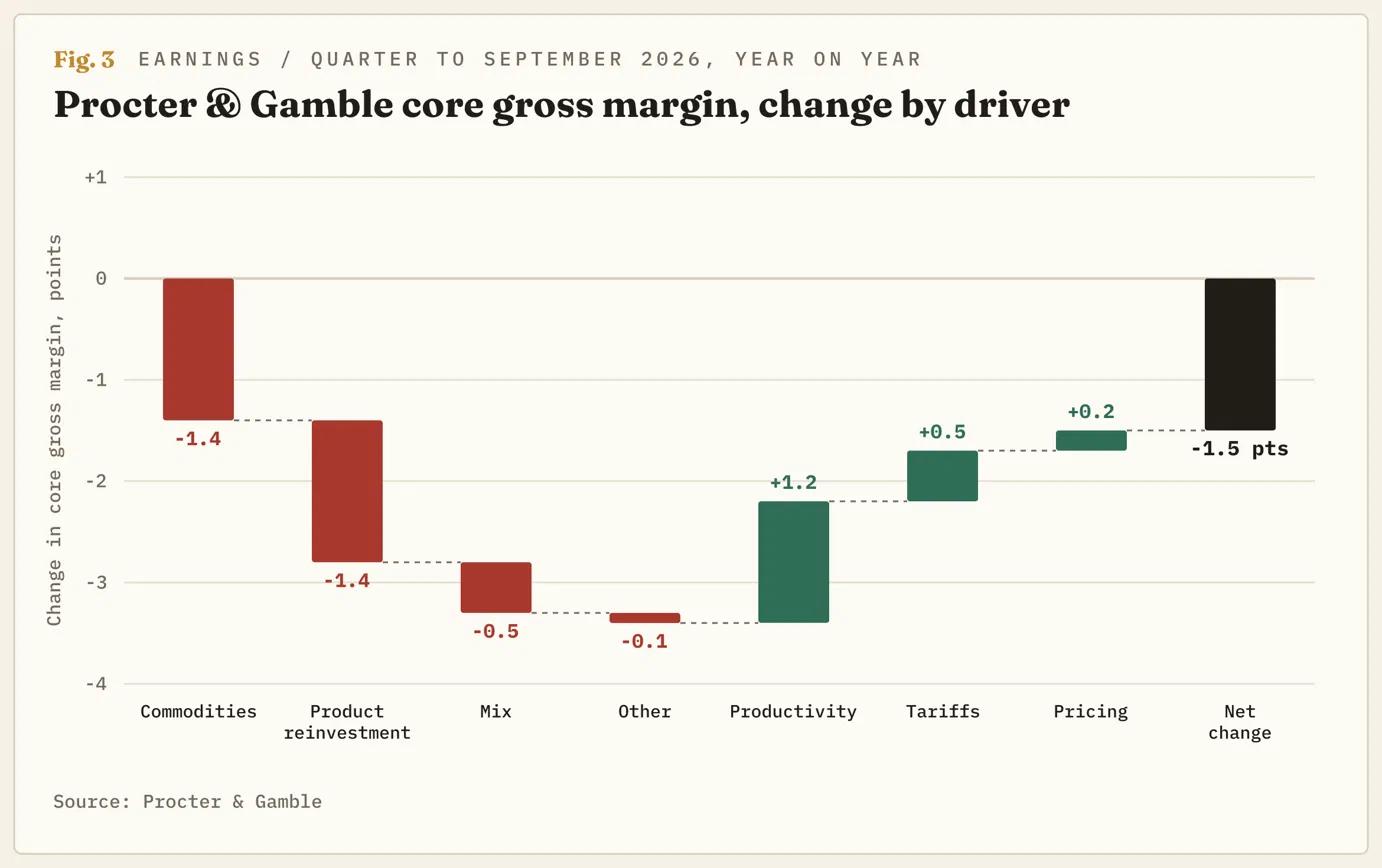
Sales increased 4% in the quarter to September at Procter & Gamble (PG), the index's largest household-goods producer, according to its Thursday results. Higher volumes contributed 2.4 points and higher prices 0.4. Gross margin, the share of sales remaining after production costs, contracted 1.5 points. Commodity costs reduced it by 1.4 points, while pricing restored 0.2. Assuming Brent remains at $100, the company now projects an after-tax cost of $1.4 billion for raw materials, energy and freight this fiscal year, compared with $1 billion expected in July. Recovering that cost "will take record productivity levels", Chief Financial Officer Andre Schulten said. He added that "the second component is pricing with innovation", and that "the third component here is time".
With its margin at 6.3%, against 6.5% a year earlier, the index's Consumer Staples sector faces the same pattern: higher sales volumes at unchanged prices as costs climb. Philip Morris International (PM) offers a different outcome. It increased cigarette prices 8.9%, maintained shipments at the year-earlier level and lifted gross profit 6.7%. That is the pricing power of nicotine. General Motors (GM), meanwhile, estimated this year's commodity, freight and memory-chip costs at about $2 billion. The prices commanded by its trucks helped raise its North American margin by 2.5 points. Businesses unable to replicate those two companies' actions absorb the gap. September's PPI showed gasoline retailing margins down 30.3% despite a 20.3% rise in gasoline prices. In that line of the release, the margin absorbs the gap directly.
2027: Pricing Takes Time
Commodity costs at Procter & Gamble represented 5% of earnings in the reported quarter and 8% for the year. More of the burden falls in the remaining three quarters than in the first. To recover those costs, price changes are "generally timed with modular resets", when retailers rebuild their shelves. The increases therefore reach the CPI in 2027. According to Schulten, "there is no way to recover this level of commodity pressure without pricing", and "the industry generally is pricing up". He delivered that message while saying, "I cannot announce pricing, and I will not announce pricing in any way, shape, or form."
For 2027, analysts project 16% earnings growth for the S&P 500 against revenue growth of 9.5%. Those forecasts imply another expansion in margins. Yet its soap, cigarette and truck producers say the year begins with costs above last year's levels. The index trades at 19 times forecast earnings for the next twelve months, slightly below its five-year average. That places the risk in the earnings assumptions rather than the multiple investors pay. The Fed's next meeting is on October 28, and most committee members have publicly indicated that they expect another rate increase by year-end. Price rises arriving in 2027 will feed into the CPI that the Fed is raising rates to contain. Companies, meanwhile, offer only the next shelf reset as a timetable.
7,700 Defines the Technical Outlook
About half the S&P 500's advance from its September low to the October 6 record has been erased. For the second time since September, it trades just below its 50-day average. Before this week's results, the daily Stochastic Relative Strength Index (Stoch RSI), a momentum indicator, had turned lower from near 70. The retreat thus began before results from Procter & Gamble. Since the March low, the pattern has consisted of successively higher lows above a rising 50-day average, with a 7,800 ceiling breached only during the move to the record. The key level is 7,700, where that average sits.
Closing levels below 7,700 leave the bias to the downside. The initial test comes at 7,500, September's low and the latest higher low in the sequence. A close beneath it would establish the first lower low since March. Around 7,300, the 200-day average marks the point where the 2022 experience of six quarters of shrinking margins becomes the chart's base case rather than a historical comparison. A daily close above 7,800 would invalidate that view. Such a move would mean investors are paying for energy and technology margins while looking past the other nine sectors. Alternatively, falling Oil could narrow the gap from above, reducing consumer companies' costs before eroding energy-sector profits. October's CPI is due on November 10, followed by the PPI on November 13. A gap that closes from above is the outcome the index can afford.
POPULAR ARTICLES
10.8200 Area: USD/CHF Price Forecast as Bulls Defend 50-Day SMA26.6640: Chinese Yuan edges towards this level against US Dollar – UOB3$55 breached: XAG/USD bears eye $50 in Silver Price Forecast4Gold falls despite lower yields as US Treasuries attract safe-haven flows5Hawkish BoK hold underpins South Korean Won gains against US Dollar – Societe Generale6December hike indicated by gradual European Central Bank tightening – Rabobank7Forex Today: PMI Data in Focus!8Third-quarter inflation slowdown weighs on New Zealand Dollar9Indonesian Rupiah: Currency gains policy mix support as challenges remain – Commerzbank
LIVE QUOTES


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us












The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: [email protected]
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: [email protected]
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: [email protected]
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: [email protected]
Copyright © TMGM. All rights reserved