

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
The Japanese Yen barely moves as a Bank of Japan deputy talks up inflation risk
- USD/JPY barely moves near 158.00 as BoJ Deputy Governor Himino flags inflation risk.
- Japan's core inflation under 2% for seven months, through two BoJ hikes.
- September core CPI, due Thursday, is forecast at 2.1% after 1.7%.
The Bank of Japan (BoJ) has raised its rate twice this year, to 1.25% in September, with core inflation below its 2% target in each of the seven months to August. USD/JPY trades near 158.00 and has held between 157.50 and 159.00 for 12 sessions. BoJ Deputy Governor Himino said on Wednesday that underlying inflation is almost at 2% and that the risks to prices lean higher, and the pair stayed inside the same range.
Deputy Governor Himino warned about moving too late, eight weeks before the next likely move
Deputy Governor Himino said upside risks to inflation remain high and that adjusting policy too late could let them materialise. He described financial conditions as still accommodative, with real interest rates low and bank lending growing quickly. The Yen gained a little on the remarks and gave it back inside Wednesday's range.
Kyodo expects the BoJ to hold at 1.25% when it decides on October 30, and swaps price a hike for December 18 at about 75%-80%. Japan's September trade deficit came in at ¥536.6 billion, about three times the ¥181 billion forecast, with exports up 16.7% from a year earlier against a 20.1% forecast. A deficit that size is Yen that has to be sold to pay for imports, whatever Deputy Governor Himino says about inflation.
The Yen is held between a rate gap and a finance ministry
Japan's Ministry of Finance bought ¥11.74 trillion of Yen between April 28 and May 27, and in late July it acted jointly with the US Treasury after USD/JPY went above 160.00. Finance Minister Katayama renewed his warnings on October 15 after US inflation came in hot, and USD/JPY hasn't traded above 159.00 since.
That leaves the pair in a box. A Treasury 10-year near 5.1%, against a Japanese 10-year that reached about 3.1% on October 7 and was back near 2.9% by October 16, keeps USD/JPY from falling far, and the threat of another round of buying keeps it from rising far. Finance Minister Katayama doesn't name an intervention level, and the market has fixed on the one USD/JPY crossed before the last intervention.
A 2.1% core reading would clear the target with electricity still subsidised
Japan's national Consumer Price Index (CPI) for September comes at 23:30 GMT on Thursday, with core inflation excluding fresh food forecast at 2.1% after 1.7%. Headline inflation was 1.9% in August, and the measure excluding food and energy was also 1.9%. Electricity prices fell 2.4% from a year earlier in August as government energy subsidies took effect, which is part of why the core rate stayed under 2% through both of the BoJ's hikes.
The BoJ's September hike passed 7-2, with the two dissenters arguing that inflation was still below 2%. A reading of 2.1% would take that argument away a month after it was made and a week before the next decision.
Even so, a strong figure would firm the December hike rather than bring one forward to October 30, so it may do less for the Yen than the headline suggests. The University of Michigan survey at 14:00 GMT on Friday is forecast to show US households expecting 4.7% inflation over the next year and 3.5% over five, and US yields are what keep USD/JPY closer to 160.00 than to 155.00.
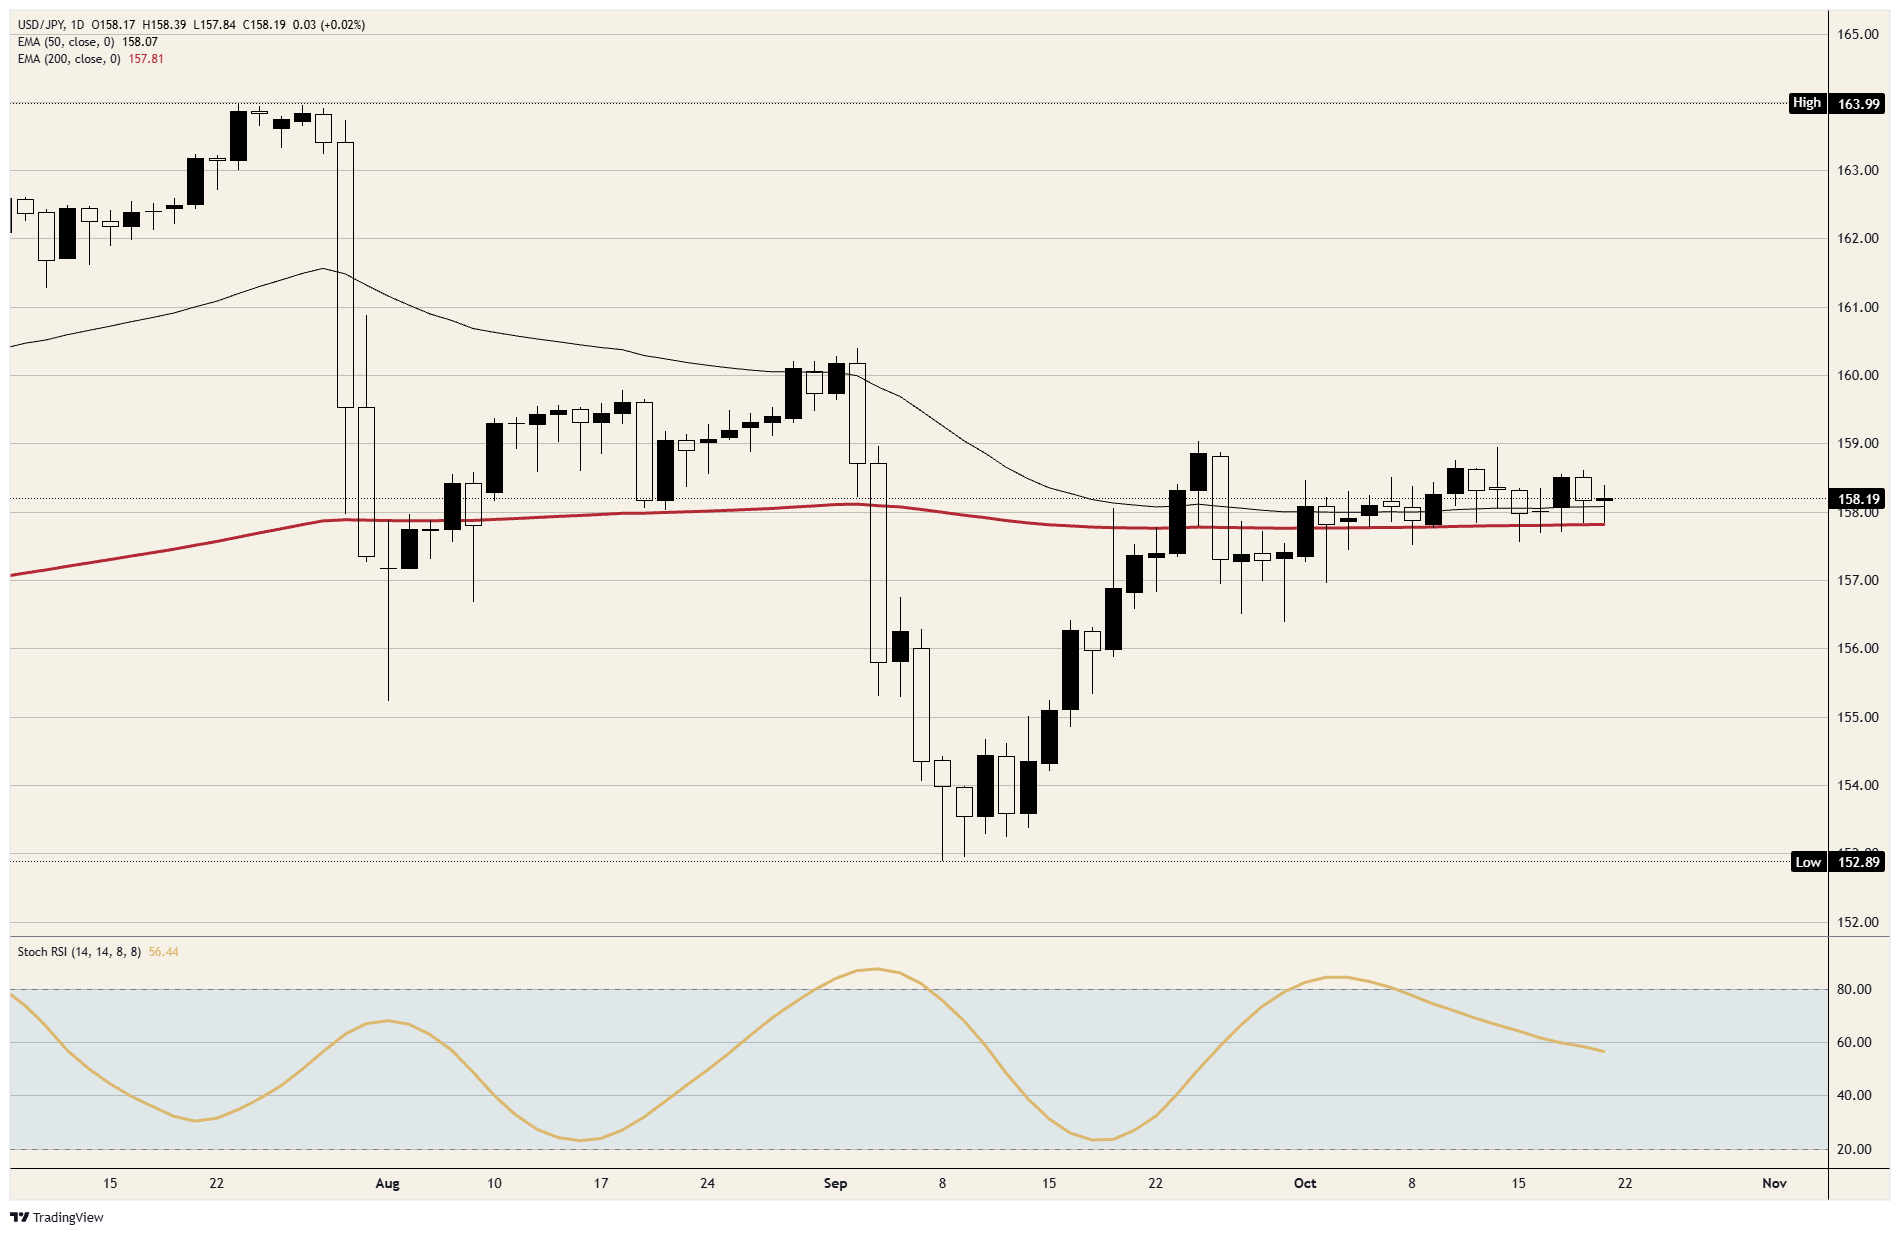
The Yen's levels inside the 157.50-159.00 range
Resistance: 158.50 stopped the highs on Monday and Tuesday. 159.00 has capped every session since October 6, with the October 14 high just under it, and 160.00 is the level USD/JPY broke before the July intervention.
Support: Wednesday's low stopped on the 200-day Exponential Moving Average (EMA), just under 158.00. 157.50 has held every session since October 6, and the October 2 low sits just under 157.00.
Bias: Long while 157.50 holds on a closing basis. The objectives are 158.50 and then 159.00. The daily Stochastic Relative Strength Index (Stoch RSI) has fallen to about 56 from above 80 in early October, so momentum is fading inside the range rather than building toward a break. A daily close below 157.50 ends the long.
USD/JPY daily chart
Japanese Yen FAQs
The Japanese Yen (JPY) is one of the world’s most traded currencies. Its value is broadly determined by the performance of the Japanese economy, but more specifically by the Bank of Japan’s policy, the differential between Japanese and US bond yields, or risk sentiment among traders, among other factors.
One of the Bank of Japan’s mandates is currency control, so its moves are key for the Yen. The BoJ has directly intervened in currency markets sometimes, generally to lower the value of the Yen, although it refrains from doing it often due to political concerns of its main trading partners. The BoJ ultra-loose monetary policy between 2013 and 2024 caused the Yen to depreciate against its main currency peers due to an increasing policy divergence between the Bank of Japan and other main central banks. More recently, the gradually unwinding of this ultra-loose policy has given some support to the Yen.
Over the last decade, the BoJ’s stance of sticking to ultra-loose monetary policy has led to a widening policy divergence with other central banks, particularly with the US Federal Reserve. This supported a widening of the differential between the 10-year US and Japanese bonds, which favored the US Dollar against the Japanese Yen. The BoJ decision in 2024 to gradually abandon the ultra-loose policy, coupled with interest-rate cuts in other major central banks, is narrowing this differential.
The Japanese Yen is often seen as a safe-haven investment. This means that in times of market stress, investors are more likely to put their money in the Japanese currency due to its supposed reliability and stability. Turbulent times are likely to strengthen the Yen’s value against other currencies seen as more risky to invest in.
Top Articles
1The Japanese Yen barely moves as a Bank of Japan deputy talks up inflation risk2AUD/JPY Price Forecast: Double bottom puts 113.50 in bulls' sights3Chinese Yuan: Gradual gains toward 6.6640 against US Dollar – UOB4GBP/JPY Price Forecast: Doji tests bulls’ resolve below 212.005The Euro gets the PMIs first and France's credit rating over the weekend6Australian Dollar defies Iran war jitters as RBA hike bets double7The British Pound goes into retail sales with its November hike already priced8New Zealand's CPI inflation eases to 3.7% YoY in Q3, vs 3.8% expected9Indonesian Rupiah: Depreciation bias with MSCI risk – MUFG
LIVE QUOTES


ALL ABOUT FOREX
Margin Call Meaning: What It Is, What Triggers It and How to Avoid One
Top 15 Weakest Currencies in the World
Top 15 Strongest Currencies in the World
Is Forex Trading Halal?
Best Time to Trade Forex
Forex Trading vs Futures Trading
Forex Trading vs Stock Trading
Forex Trading vs Crypto Trading
Is Forex Trading Profitable In 2026?
Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us












The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: [email protected]
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: [email protected]
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: [email protected]
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: [email protected]
Copyright © TMGM. All rights reserved