

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
Euro sheds early gains as oil prices rise and French fiscal risks weigh
- Multiple headwinds erase the Euro’s initial advance against the US Dollar.
- High oil prices and fiscal concerns in France maintain pressure on the Euro.
- Interest rates are expected to remain on hold at both the Fed and the ECB next week.
EUR/USD is broadly flat near 1.1234. During Thursday’s European session, the Euro (EUR) has relinquished its early gains against the US Dollar (USD). Several headwinds facing the single currency are weighing on the major pair.
Euro sentiment weakens as energy costs and French debt weigh
Sentiment has been the main driver of the Euro’s latest decline, according to strategists at Danske Bank. They stress that “the decline in the pair is driven by the combination of high energy prices and EUR-pessimism on the back of French debt worries.” In their view, these pressures have deepened the existing caution towards the single currency. Investors remain reluctant to increase Euro exposure, even without a clear directional catalyst from broader markets.
WTI Oil is trading 2% higher near $99.50 at the time of writing. More expensive oil is negative for the Euro because Europe depends heavily on imports to cover its energy needs.
Friday’s preliminary October PMI releases for the Eurozone and the United States (US) are also in focus. Aggregate business activity in both economies is expected to have continued expanding, although at a moderate rate.
Next week, monetary policy decisions from the European Central Bank (ECB) and the Federal Reserve (Fed) will provide key catalysts for the Euro and the US Dollar. Both central banks are expected to keep interest rates on hold.
EUR/USD: Technical Outlook
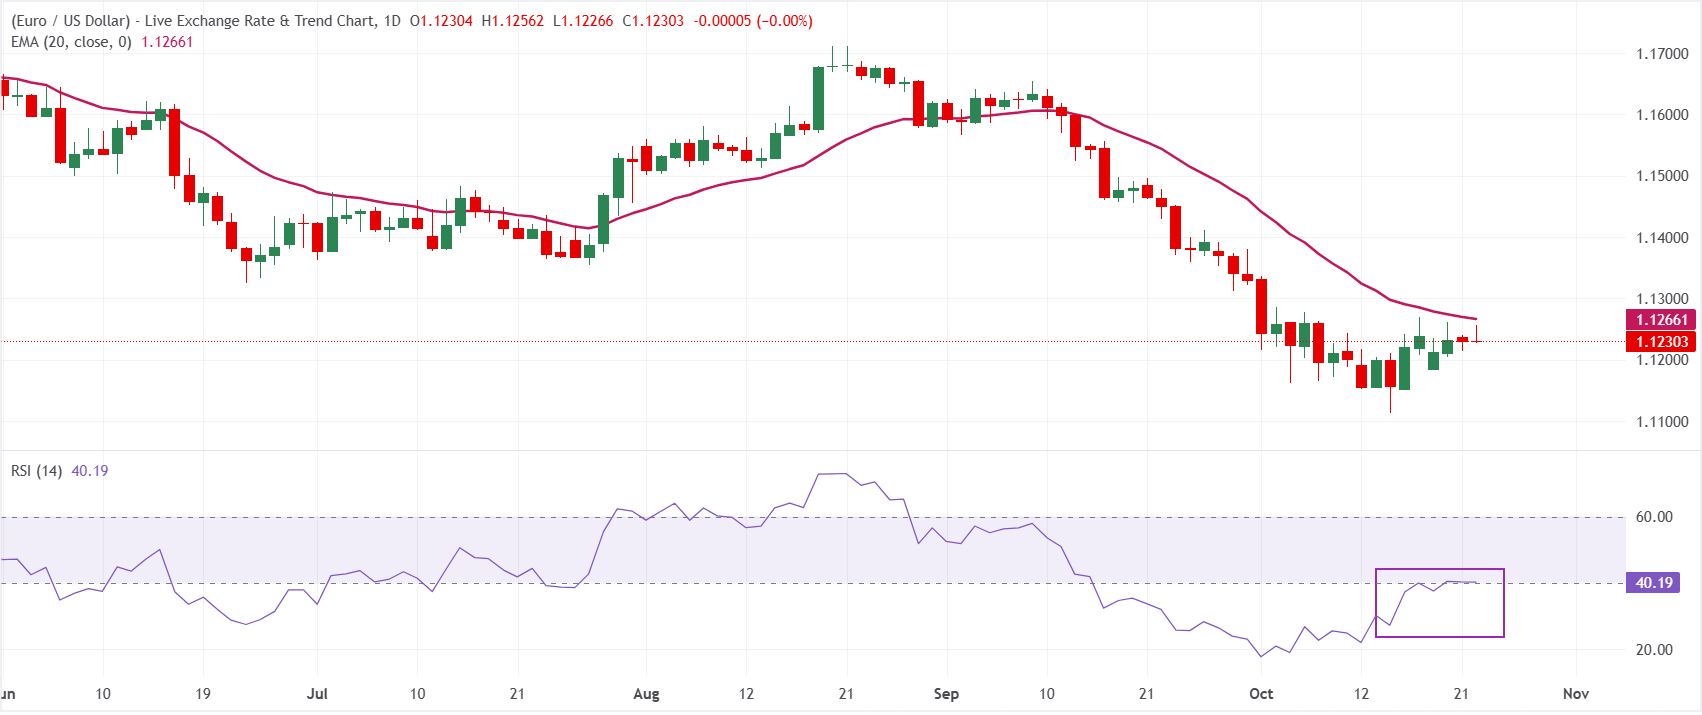
At 1.1231 on the daily chart, EUR/USD remains below its 20-day Exponential Moving Average (EMA) of 1.1266. This maintains a mildly bearish outlook. The short-term EMA continues to cap the pair, indicating selling into rallies. Meanwhile, a Relative Strength Index (RSI) reading near 40 points to weak but stabilising downside momentum, rather than outright oversold conditions.
Immediate resistance lies at the 20-day EMA of 1.1266. Bulls must recover that level to relieve the prevailing pressure and create scope for a more sustained rebound. With no nearby measured support levels in the data set, spot remains exposed to further declines towards earlier price lows. Sentiment is likely to remain fragile for as long as EUR/USD stays below the short-term EMA.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Euro: Frequently Asked Questions
20 European Union countries use the Euro as members of the Eurozone. Only the US Dollar is traded more heavily worldwide. The Euro represented 31% of all foreign exchange transactions in 2022, with average daily turnover exceeding $2.2 trillion. An estimated 30% of all transactions involve EUR/USD, making it the world’s most actively traded currency pair. It is followed by EUR/JPY (4%), EUR/GBP (3%) and EUR/AUD (2%).
Based in Frankfurt, Germany, the European Central Bank (ECB) serves as the Eurozone’s reserve bank. Responsibility for setting interest rates and managing monetary policy rests with the ECB. Maintaining price stability is its core mandate, whether through containing inflation or supporting growth. Interest rate increases and cuts are its main policy tools. Higher relative rates, or expectations of rate increases, generally support the Euro; the reverse also applies. Monetary policy is decided by the ECB Governing Council, which meets eight times a year. The decision-makers comprise the heads of Eurozone national banks and six permanent members, among them ECB President Christine Lagarde.
The Harmonized Index of Consumer Prices (HICP) measures Eurozone inflation and is a key economic indicator for the Euro. An inflation reading above expectations, particularly one exceeding the ECB’s 2% target, obliges the central bank to increase interest rates to restore control over prices. When interest rates are relatively high compared with those elsewhere, the Euro generally benefits. Higher rates make the region a more attractive destination for global investors’ funds.
By indicating the economy’s health, data releases can move the Euro. GDP, Manufacturing and Services PMIs, employment figures and consumer sentiment surveys can all help determine the single currency’s direction. Economic strength supports the Euro by drawing in foreign investment. It may also prompt the ECB to raise interest rates, directly strengthening the currency. Weak economic readings, by contrast, are likely to weigh on the Euro. Particular weight is attached to figures from Germany, France, Italy and Spain. These four largest euro area economies together represent 75% of the Eurozone’s economy.
The Trade Balance is another important release for the Euro. Over a specified period, it records the gap between a country’s export earnings and its spending on imports. Strong foreign demand for a country’s exports creates additional demand for its currency as overseas buyers purchase those goods, lifting the currency’s value. A positive net Trade Balance therefore supports a currency, while a negative balance has the opposite effect.
POPULAR ARTICLES
1Gold: Range ceiling points to pullback risk – Societe Generale2Australian Dollar’s corrective pullback from monthly high stalls amid RBA hawkishness and USD weakness31.4000 Support in Focus: USD/CAD Price Forecast After Drop Below 50-Day EMA40.7070 cap in focus as overbought Australian Dollar rallies against US Dollar – UOB5EUR/CAD retreats as higher crude oil prices support Canadian Dollar against Euro6South African Rand: Fiscal advances and easing inflation pressures – Commerzbank7$99 breached: WTI Oil rallies as Middle East war threatens to grow more complex8Euro sheds early gains as oil prices rise and French fiscal risks weigh9Dow Jones futures edge lower as tech-led rally loses steam


Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us












The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: [email protected]
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: [email protected]
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: [email protected]
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: [email protected]
Copyright © TMGM. All rights reserved