

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
Bank of Japan deputy highlights inflation risk as Japanese Yen holds steady
- 158.00 remains the anchor for USD/JPY, little changed despite BoJ Deputy Governor Himino's inflation warning.
- 2% remains out of reach for Japan's core inflation for seven months, despite two BoJ rate increases.
- 2.1% is the forecast for September core CPI due on Thursday, up from 1.7%.
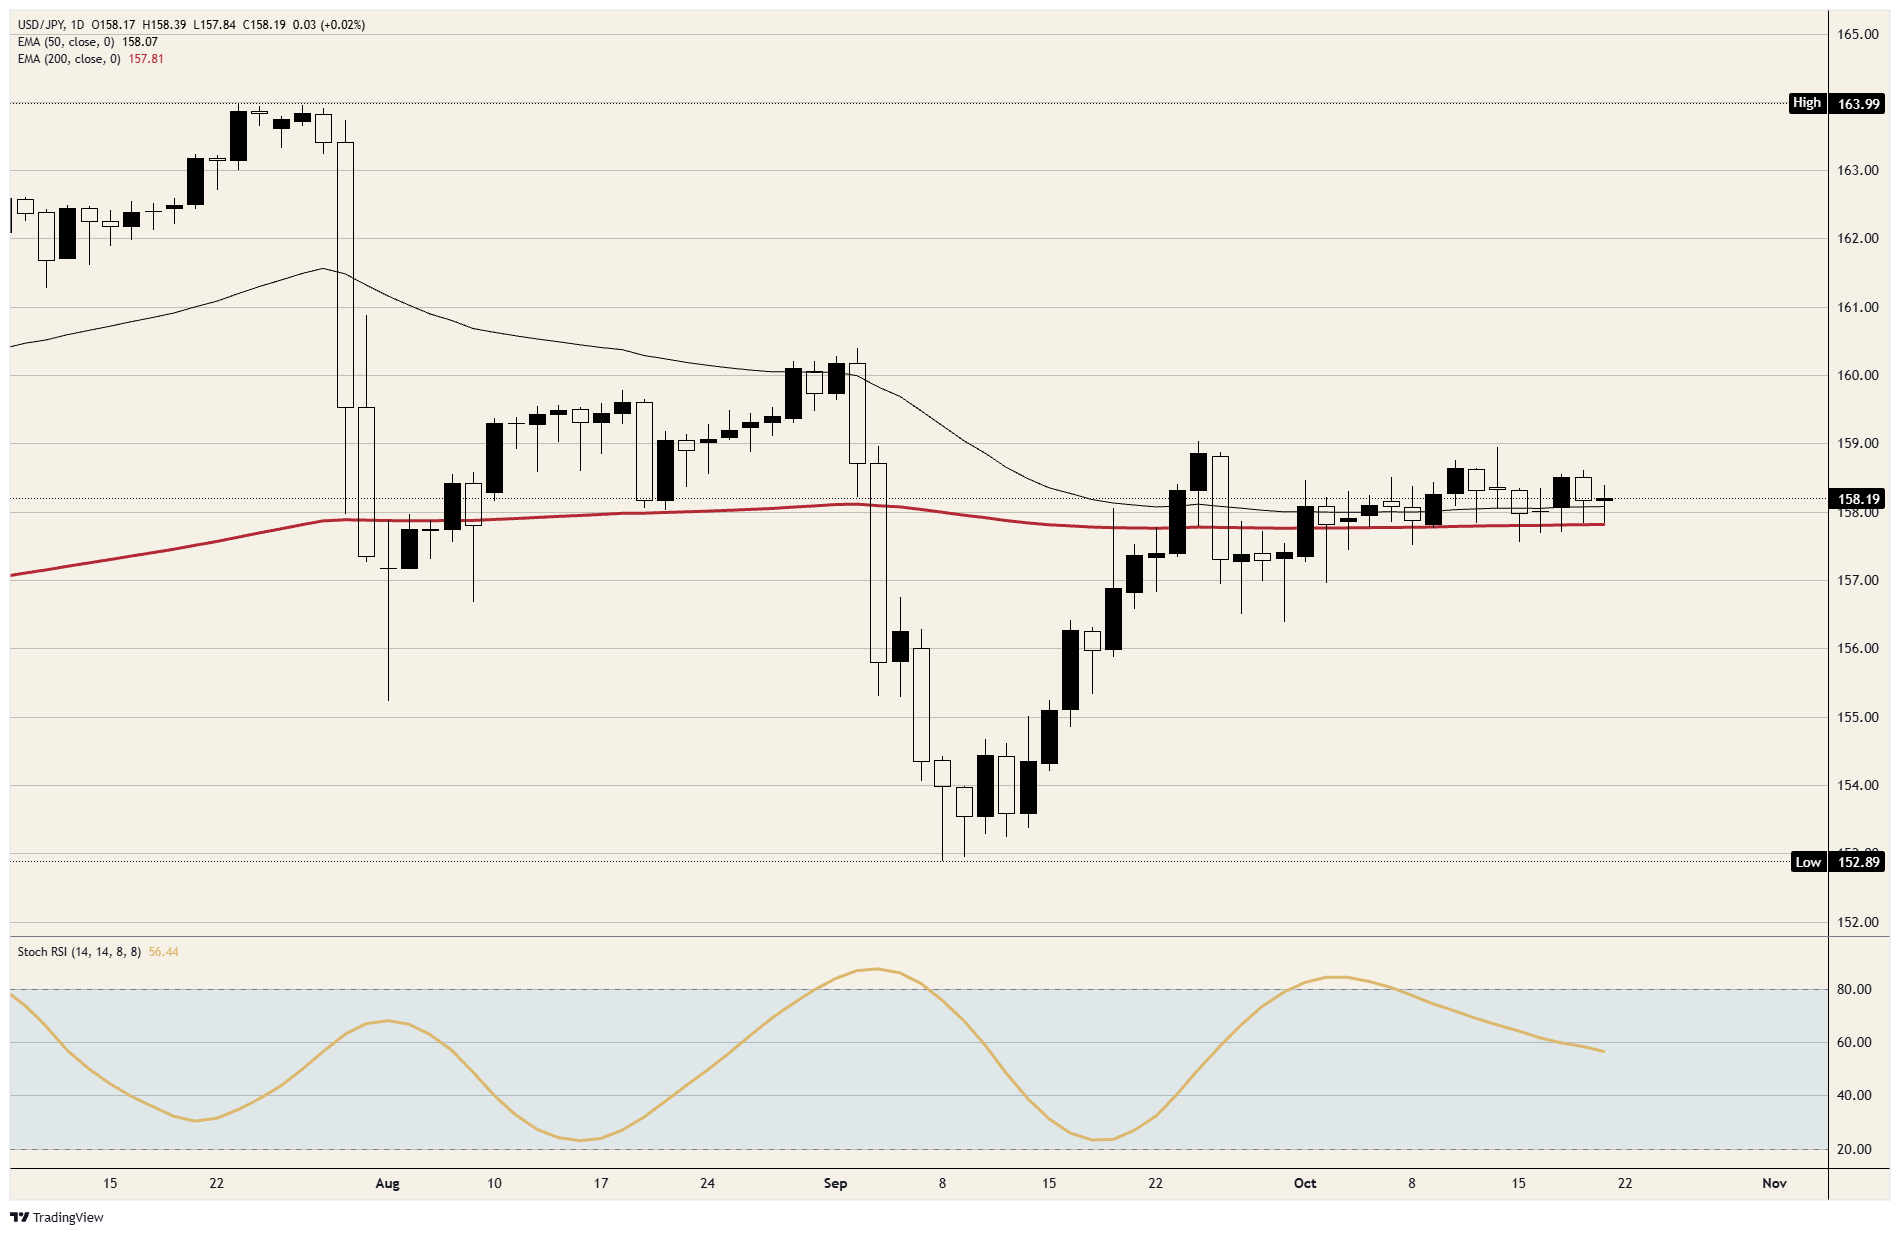
1.25% is the Bank of Japan's (BoJ) policy rate following its September increase. The central bank has lifted rates twice this year, although core inflation remained below its 2% target throughout the seven months to August. Near 158.00, USD/JPY has spent 12 sessions within a 157.50 to 159.00 band. On Wednesday, BoJ Deputy Governor Himino put underlying inflation at almost 2% and said price risks were skewed upwards. His comments left the pair within that range.
Eight weeks before the next likely move, Deputy Governor Himino warns against delay
Delaying a policy adjustment could allow elevated upside inflation risks to materialise, Deputy Governor Himino said. Low real interest rates and rapid bank lending growth meant financial conditions remained accommodative, in his assessment. The Yen briefly strengthened in response before surrendering those gains within Wednesday's trading range.
For the 30 October decision, Kyodo expects an unchanged BoJ rate of 1.25%. Swaps put the probability of an increase on 18 December at about 75%-80%. Meanwhile, Japan reported a September trade deficit of ¥536.6 billion, roughly three times the ¥181 billion forecast. Exports rose 16.7% year on year, short of the projected 20.1%. Regardless of Deputy Governor Himino's inflation comments, financing imports with a deficit of that scale requires Yen selling.
Yield gap and finance ministry intervention constrain the Yen
Between 28 April and 27 May, Japan's Ministry of Finance purchased ¥11.74 trillion of Yen. It then took joint action with the US Treasury in late July after USD/JPY exceeded 160.00. Following the hot US inflation reading, Finance Minister Katayama repeated his warnings on 15 October. The pair has remained at or below 159.00 since.
These opposing forces leave USD/JPY confined to a range. The US Treasury 10-year yield stands near 5.1%, while Japan's 10-year yield returned to around 2.9% by 16 October after reaching about 3.1% on 7 October. That gap limits the pair's downside; the prospect of renewed Yen purchases restricts its upside. Although Finance Minister Katayama has specified no intervention threshold, traders have focused on the level breached before the previous intervention.
2.1% core CPI would exceed target despite electricity subsidies
2.1% is the forecast for Japan's September core inflation, excluding fresh food, against the previous 1.7%. The national Consumer Price Index (CPI) release is scheduled for Thursday at 23:30 GMT. August headline inflation stood at 1.9%, matching the measure excluding food and energy. With government energy subsidies taking effect, electricity prices dropped 2.4% year on year in August. That partly explains why core inflation stayed below 2% through both BoJ rate increases.
A 7-2 vote approved the BoJ's September rate increase. Both dissenters cited inflation remaining below 2%. Should the reading reach 2.1%, that objection would no longer hold, a month after it was raised and a week ahead of the next decision.
Even a robust release, however, would reinforce the case for a December increase rather than advance it to 30 October. Its support for the Yen may therefore be weaker than the headline implies. Due on Friday at 14:00 GMT, the University of Michigan survey is forecast to put US household inflation expectations at 4.7% for the next year and 3.5% over five years. US yields remain the reason USD/JPY sits nearer 160.00 than 155.00.
157.50-159.00: Key levels for the Yen
Resistance: Monday's and Tuesday's highs met resistance at 158.50. Every session since 6 October has been capped at 159.00, with the 14 October peak marginally below that mark. Before July's intervention, USD/JPY had breached 160.00.
Support: Just below 158.00, the 200-day Exponential Moving Average (EMA) arrested Wednesday's decline. Support at 157.50 has survived every session since 6 October. The low recorded on 2 October lies slightly below 157.00.
Bias: The long bias holds while closing levels remain above 157.50, targeting 158.50 first and 159.00 next. Momentum is weakening within the range rather than gathering towards a breakout: the daily Stochastic Relative Strength Index (Stoch RSI) has dropped to about 56 from above 80 in early October. A daily close below 157.50 invalidates the long position.
USD/JPY: Daily price chart
Japanese Yen: Frequently asked questions
Among the world's most actively traded currencies, the Japanese Yen (JPY) takes its broad direction from Japan's economic performance. More specific influences include Bank of Japan policy, the gap between Japanese and US bond yields and traders' appetite for risk, alongside other factors.
Currency control forms part of the Bank of Japan's mandate, making its actions a major influence on the Yen. Direct currency-market intervention has occurred on occasion, usually to weaken the currency. Political sensitivities among Japan's main trading partners nevertheless discourage frequent intervention. From 2013 to 2024, the BoJ's ultra-loose monetary stance increasingly diverged from those of other leading central banks, driving Yen depreciation against its major peers. The more recent gradual withdrawal of that policy has provided the currency with some support.
A widening gap between US and Japanese 10-year bond yields over the past decade favoured the US Dollar over the Japanese Yen. Behind that gap was growing policy divergence, particularly with the US Federal Reserve, as the BoJ maintained its ultra-loose monetary stance. The differential is now narrowing following the BoJ's 2024 decision to withdraw that stance gradually and interest-rate reductions by other major central banks.
During periods of market stress, investors are more inclined to allocate money to the Japanese Yen because of its perceived stability and reliability. This underpins its frequent status as a safe-haven investment. Market turbulence is therefore likely to lift the Yen against currencies viewed as riskier investments.
POPULAR ARTICLES
1Iran calls on US to lift blockade as proof it wants peace2Below $4,150: gold holds steady as traders weigh Fed rate path and Middle East risk3Bank of Japan deputy highlights inflation risk as Japanese Yen holds steady4113.50 in View: AUD/JPY Price Forecast Points to Double-Bottom Upside56.6640: UOB sees gradual Chinese Yuan gains against US Dollar6Below 212.00: GBP/JPY Price Forecast as Doji challenges bullish conviction7Euro awaits PMIs first, then France’s credit rating over the weekend8RBA hike bets double: Australian Dollar shrugs off Iran war fears9November hike already priced in as British Pound awaits retail sales
LIVE QUOTES

Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us












The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: [email protected]
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: [email protected]
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: [email protected]
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: [email protected]
Copyright © TMGM. All rights reserved