
News & AnalysisCareer

At around 101.68, the US Dollar Index (DXY) is slightly lower during Wednesday’s European session as markets await Meta’s Q3 earnings later in the day. Measuring the Greenback against six major currencies, the index remains near last week’s low of 101.50, its weakest level in almost three weeks. Trading against its peers is cautious ahead of the results.
Meta’s results are expected to have a substantial influence on the US Dollar and United States (US) Treasury yields. Market experts have recently argued that US hyperscalers’ spending on Artificial Intelligence (AI) infrastructure has become a central driver of both.
Concerns about AI growth have pulled US bond yields and the US Dollar back from their recent peaks.
Against the major currencies listed below, the US Dollar (USD) recorded the percentage changes shown over the last 7 days. Its weakest performance was against the New Zealand Dollar.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | -0.29% | -1.08% | -0.25% | -1.22% | -0.73% | -1.36% | -1.01% | |
| EUR | 0.29% | -0.79% | 0.04% | -0.94% | -0.43% | -1.07% | -0.70% | |
| GBP | 1.08% | 0.79% | 0.85% | -0.12% | 0.41% | -0.28% | 0.06% | |
| JPY | 0.25% | -0.04% | -0.85% | -0.98% | -0.47% | -1.09% | -0.75% | |
| CAD | 1.22% | 0.94% | 0.12% | 0.98% | 0.51% | -0.08% | 0.20% | |
| AUD | 0.73% | 0.43% | -0.41% | 0.47% | -0.51% | -0.68% | -0.33% | |
| NZD | 1.36% | 1.07% | 0.28% | 1.09% | 0.08% | 0.68% | 0.35% | |
| CHF | 1.01% | 0.70% | -0.06% | 0.75% | -0.20% | 0.33% | -0.35% |
Percentage movements between the major currencies are displayed in the heat map. Select the base currency in the left-hand column and the quote currency in the top row. Selecting the US Dollar on the left and following that row across to the Japanese Yen, for instance, gives the percentage change for USD (base)/JPY (quote).
Following the recent correction, MUFG analysts described US financial markets as “a major beneficiary of strong foreign investor demand driven by AI-related optimism.” They pointed to foreign investors’ purchases of “USD942 billion of US equities in the twelve months to July, while purchases of US corporate bonds increased sharply to USD452 billion over the same period.” In MUFG’s view, these “sizeable inflows highlight how the USD has become increasingly tied to investors’ search for higher returns in US financial markets, rather than benefiting from its traditional safe-haven status.” The analysts nevertheless warned that “this dynamic also leaves the USD more exposed to a reversal if sentiment towards AI deteriorates.”
Meta’s guidance on AI-related expenditure will come under close scrutiny in financial markets. INDMoney puts Meta’s capital expenditure outlook for 2026 at $130 billion to $145 billion. The company’s presentation reported first-half spending of $50.918 billion. If Q3 spending meets the $41.68 billion estimate, the remaining requirement is straightforward to calculate.
Any indication in Meta’s guidance commentary that its AI infrastructure spending is slowing would put pressure on the outlook for the US Dollar.
Friday brings the preliminary US S&P Global PMI release for October, which investors are awaiting on the economic calendar. The figures are expected to indicate another expansion in overall business activity, albeit at a moderate pace.
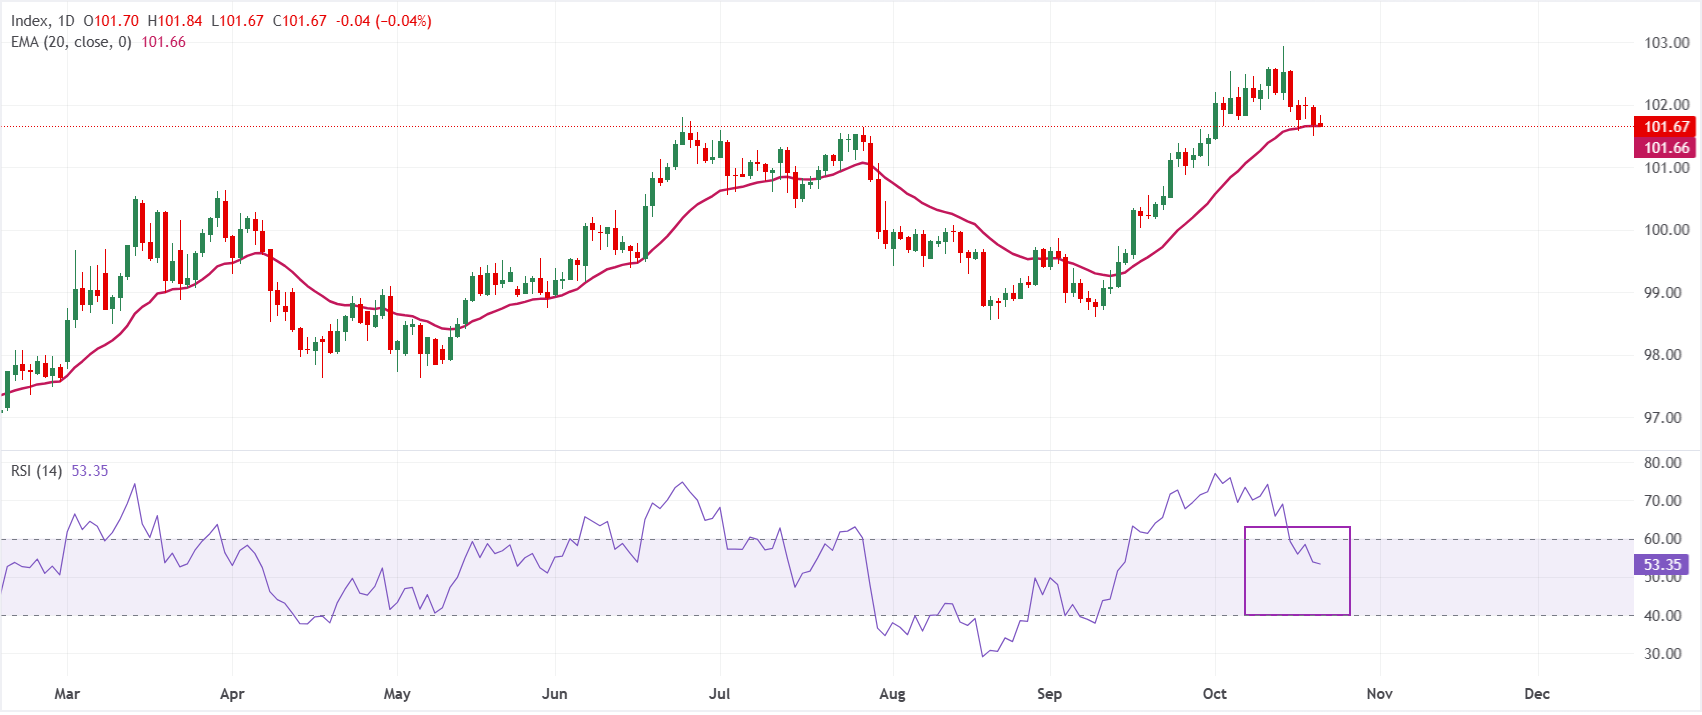
At 101.67 on the daily chart, the Dollar Index Spot remains marginally above its 20-day Exponential Moving Average (EMA) of 101.66. Support from this dynamic floor leaves the near-term bias slightly bullish. Meanwhile, a Relative Strength Index (RSI) reading of 53.39 is just above neutral, suggesting steady upward momentum without overextension as the index consolidates near recent highs.
The 20-day EMA at 101.66 provides the first downside support. A sustained move below it would undermine the positive tone and leave scope for a more pronounced retreat. As the current dataset contains no nearby technical resistance levels, traders may turn to psychological levels and previous swing highs above the market to identify possible supply zones. The existing setup nevertheless favours buying on dips while the index remains above the 101.66 area.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
As the official currency of the United States of America, the US Dollar (USD) also circulates alongside local banknotes in a significant number of other countries, serving as their ‘de facto’ currency. Data from 2022 show that it is the world’s most actively traded currency, making up over 88% of global foreign exchange turnover, equivalent to average daily transactions of $6.6 trillion. The USD replaced the British Pound as the world’s reserve currency after the Second World War. Gold backed the US Dollar for most of its history, until the Bretton Woods Agreement in 1971 brought an end to the Gold Standard.
Monetary policy, set by the Federal Reserve (Fed), is the single biggest influence on the US Dollar’s value. Price stability, meaning control of inflation, and full employment are the Fed’s two mandates. Adjusting interest rates is its main means of pursuing both objectives. If prices increase too rapidly and inflation exceeds its 2% target, the Fed will increase rates, supporting the USD. Conversely, inflation below 2% or an excessively high unemployment rate may prompt the Fed to cut interest rates, putting pressure on the Greenback.
In exceptional circumstances, the Federal Reserve can create additional Dollars and introduce quantitative easing (QE). Through QE, the Fed substantially expands the flow of credit through a financial system that has become blocked. This unconventional policy is used when credit has dried up because banks are unwilling to lend to one another for fear of counterparty default. It serves as a last resort if interest rate cuts alone are unlikely to deliver the required outcome. During the Great Financial Crisis in 2008, QE was the Fed’s preferred response to the credit crunch. The process entails creating more Dollars to purchase US government bonds, mainly from financial institutions. The US Dollar usually weakens as a result of QE.
Under quantitative tightening (QT), the reverse process, the Federal Reserve ceases purchasing bonds from financial institutions. It also refrains from reinvesting the principal repaid on its maturing bond holdings in further purchases. This is generally supportive of the US Dollar.










The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: [email protected]
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: [email protected]
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: [email protected]
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: [email protected]
Copyright © TMGM. All rights reserved


