

Trading
Explore a wide range of markets with competitive pricing, deep liquidity, and advanced trading tools.
Learn More 
Platform
Trade seamlessly with TMGM's powerful platform, built for speed, precision, and a superior trading experience.
Learn More Trading Platform
Academy
Learn the fundamentals of trading with beginner-friendly resources, including guides, webinars, and market insights.
Learn More News & Analysis
Get real-time market updates and expert analysis to stay ahead of trading opportunities
Learn More News & Analysis
About
Learn what sets TMGM apart — our global presence, regulatory strength, and commitment to innovation in trading.
Learn More Why Choose TMGM
Sponsorship
Canadian Dollar rebound: Why rate-hike bets tell only part of the story
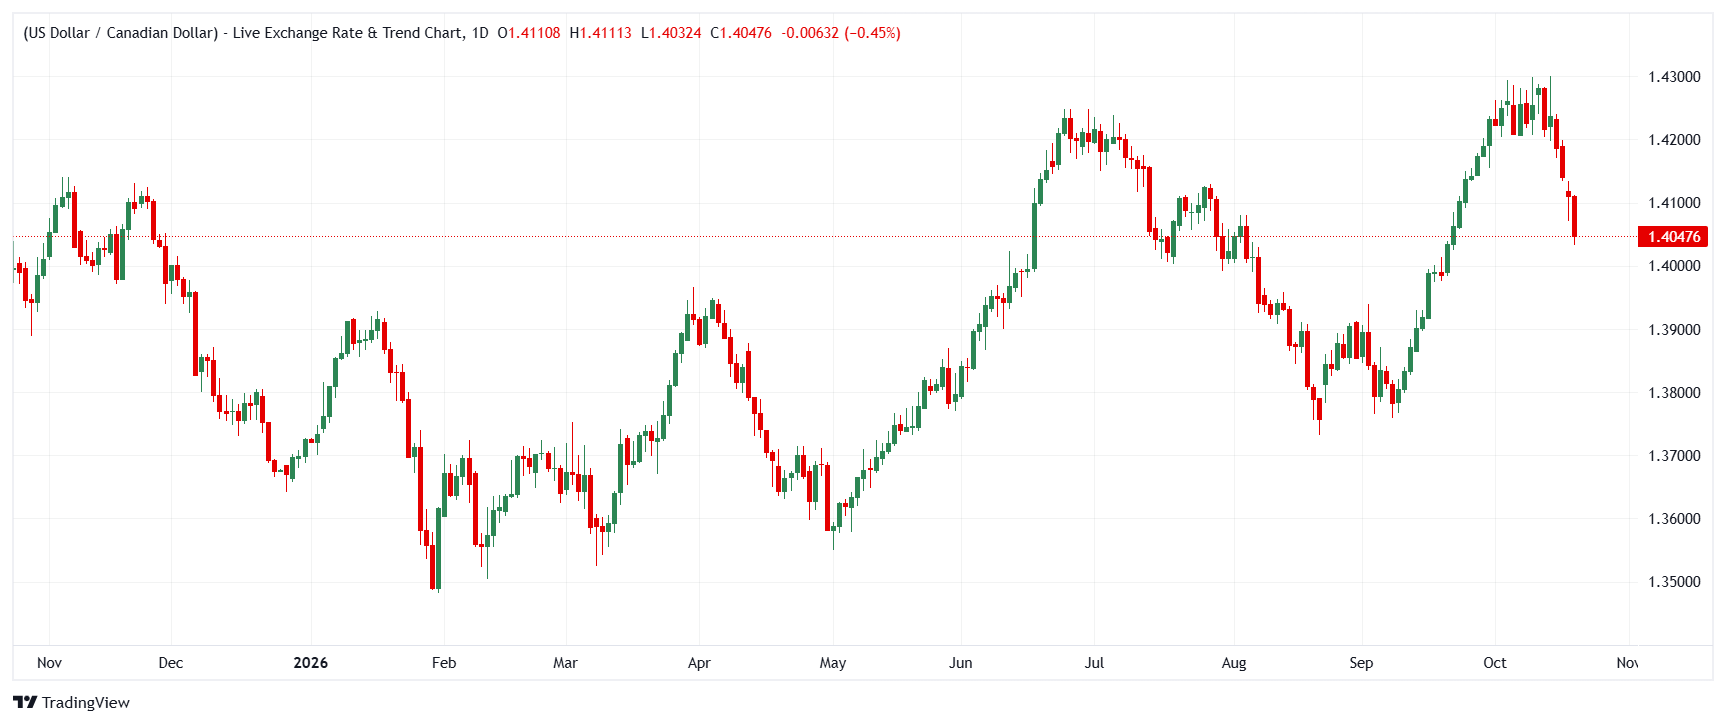
The Canadian Dollar (CAD) is in focus as USD/CAD falls to 1.4071. That is well below the 14 October high of 1.4300, after markets rapidly priced in a rate hike at the Bank of Canada's (BoC) upcoming meeting. MUFG expects the BoC is likely to raise rates, potentially followed by a second increase in December. Standard Chartered disagrees: it considers market expectations for tightening excessive and forecasts an unchanged 2.25% rate through end-2026. RBC's survey findings help explain the hawkish shift in pricing. Canadian inflation expectations are climbing sharply as trade talks with the US break down. Whether the BoC endorses those rate-hike expectations will determine CAD's next move.
2.25% Hold: Standard Chartered Sees No Need for BoC Hikes
Standard Chartered economist Dan Pan forecasts an unchanged BoC policy rate of 2.25% through end-2026 and 2027, despite market pressure for increases as soon as this month. Weak domestic demand, muted core inflation and a fragile labour market mean inflationary pressure is unlikely to broaden, in his assessment. Any October rate move would reflect "caution, not necessity," rather than a compelling economic need. He sees no strong growth catalyst to support the roughly 100bps of tightening embedded in market pricing, which he calls "excessive."
"We now expect the Bank of Canada (BoC) to stay put at 2.25% until end-2026 and 2027 (versus a cut in 2026 and a hike in 2027 previously). High oil prices have lowered the likelihood of a near-term rate cut, but sustained economic slack and contained underlying inflation still make a case for the BoC to look through near-term energy price shocks."
1.4071: MUFG Links Canadian Dollar Recovery to Hawkish Repricing
With MUFG noting a USD/CAD low of 1.4071, Lee Hardman highlights the Canadian Dollar's continuing recovery against the US Dollar, taking the pair further below its 14 October peak of 1.4300. A shift towards expectations of tighter BoC policy is driving the move. Rate markets now imply around 21bps of hikes, up from just 9bps at the end of last week, after three major Canadian banks changed their forecasts to a hike at next week's meeting. Business and consumer surveys from the BoC add support to that view, showing higher longer-term inflation expectations among households. However, September brought a second consecutive month of heavy job losses, leading Hardman to acknowledge that a hike is "not a done deal".
"The BoC has recently signalled that they are moving closer to hiking rates. If they place more weight on forward looking measures of inflation risks, and the Canadian rate market continues to price in a high probability of a hike heading into next week's meeting, we expect the BoC to pull the trigger and tighten policy."
3.7% and 3.1%: RBC Flags Higher Inflation Expectations as Trade Talks Break Down
According to Claire Fan at Royal Bank of Canada (RBC), Canadian business confidence strengthened through early August, then deteriorated sharply following the collapse of Canada-US trade talks on 21 August. As sentiment, exports and investment weakened, inflation expectations also shifted. Firms' one- and two-year-ahead expectations rebounded in September to 3.7% and 3.1% respectively, close to their spring highs. Half of surveyed firms intend to pass higher costs on to customers, a larger share than last quarter. Consumers' longer-term five-year-ahead expectations also increased substantially, reaching the same level as shorter-term expectations. The ongoing Middle East conflict was the main driver of that increase.
"Conditions among firms generally improved through early August, but evidence collected after the breakdown of Canada-U.S. trade talks on August 21 pointed to renewed weakness in sentiment, exports and investment alongside rising inflation expectations."
Three Banks, Diverging Views on the Canadian Dollar
Despite a shared backdrop of higher inflation expectations, trade uncertainty and labour-market fragility, the three banks reach very different conclusions about the BoC's response and the implications for CAD. A hike next week is MUFG's base case, with another possible before December, offering further support to the Canadian Dollar. For Standard Chartered, however, the market has priced in excessive tightening: it forecasts a hold at 2.25% through 2026 and 2027. That view implies potential CAD weakness if rate-hike expectations reverse. RBC's evidence falls between the two positions. Its data captures the inflation-expectations pressures underpinning hawkish demand for CAD, alongside fresh weakness in the real economy that makes the BoC's choice more difficult.
2.25% Hold or Hike: CAD Awaits the BoC Decision
A hold at 2.25% is one possible outcome at the BoC's upcoming meeting. The decision will determine the Canadian Dollar's near-term direction. Should the bank raise rates, as MUFG expects, it would likely confirm the market's repricing, push USD/CAD lower and encourage speculation about another increase in December. Alternatively, looking through the energy-price shock and leaving rates at 2.25%, as Standard Chartered advocates, could reverse hawkish positioning and weaken CAD. RBC's findings suggest that the inflation-risk narrative will persist under either outcome. Both firms and consumers are lifting their inflation expectations, while half of firms intend to pass on costs. That leaves the BoC under pressure and CAD responsive to every signal about the bank's next step.
(This article was created with the help of an Artificial Intelligence tool and reviewed by an editor. Know more.)
POPULAR ARTICLES
1Canadian Dollar: Energy support for economy lifts rate-hike odds – Commerzbank2Dogecoin Price Forecast: Key moving average resistance keeps DOGE in check3Weaker US Dollar lifts Silver, but Fed rate-hike risks constrain gains4Canadian Dollar rebound: Why rate-hike bets tell only part of the story5Dollar Index declines on Iran deal report before stabilising after denial61.3400: British Pound rallies as UK jobs exceed expectations and hopes for Iran deal strengthen7British Pound: Edges ahead of US Dollar – Societe Generale8WTI Oil tumbles as US-Iran compromise proposal fuels de-escalation hopes9US-Iran negotiation hopes lift euro as oil prices slide
LIVE QUOTES

Get Started!
Sign up and access the Global Markets in less than 3 minutes

Connect With Us












The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: [email protected]
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: [email protected]
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: [email protected]
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: [email protected]
Copyright © TMGM. All rights reserved