
News & AnalysisCareer

Softer housing market conditions in the United States (US) are pushing bond yields lower, leaving the US Dollar (USD) trailing its major peers.
With 10-year US Treasury yields down 0.7% at around 5.07%, the US Dollar Index (DXY) reaches a new three-week low near 101.45 during Thursday’s European session. The index measures the Greenback’s value against six major currencies.
September’s housing figures helped drive the earlier fall in yields, according to Deutsche Bank analysts, who describe the move as "supported by soft housing data for September," citing a decline in housing starts of "‑5.2% vs +1.9% exp." They also point to "a sharp slowing in pending home sales," with "their annual growth" dropping "to its lowest since 2023 at ‑12.6% yoy." In their view, this deterioration in housing conditions has bolstered modest demand for duration at the long end of the US yield curve.
At the same time, concerns surrounding Artificial Intelligence (AI) growth appear to be fading, with Meta reaffirming substantial plans to spend on AI infrastructure.
Deutsche Bank analysts report that Meta shares gained more than “+2% in after-hours trading,” following better-than-expected Q3 revenue of “$64.6bn vs $63.3bn est.” The company also provided Q4 guidance “towards the upper end of expectations” at “$73-76bn vs $73.6bn est.” Highlighting Meta’s ongoing commitment to AI investment, Deutsche Bank adds that the company “slightly boosted its 2026 capex plan from a $130bn-145bn range to $135bn-145bn,” reinforcing its focus on AI-related expenditure.
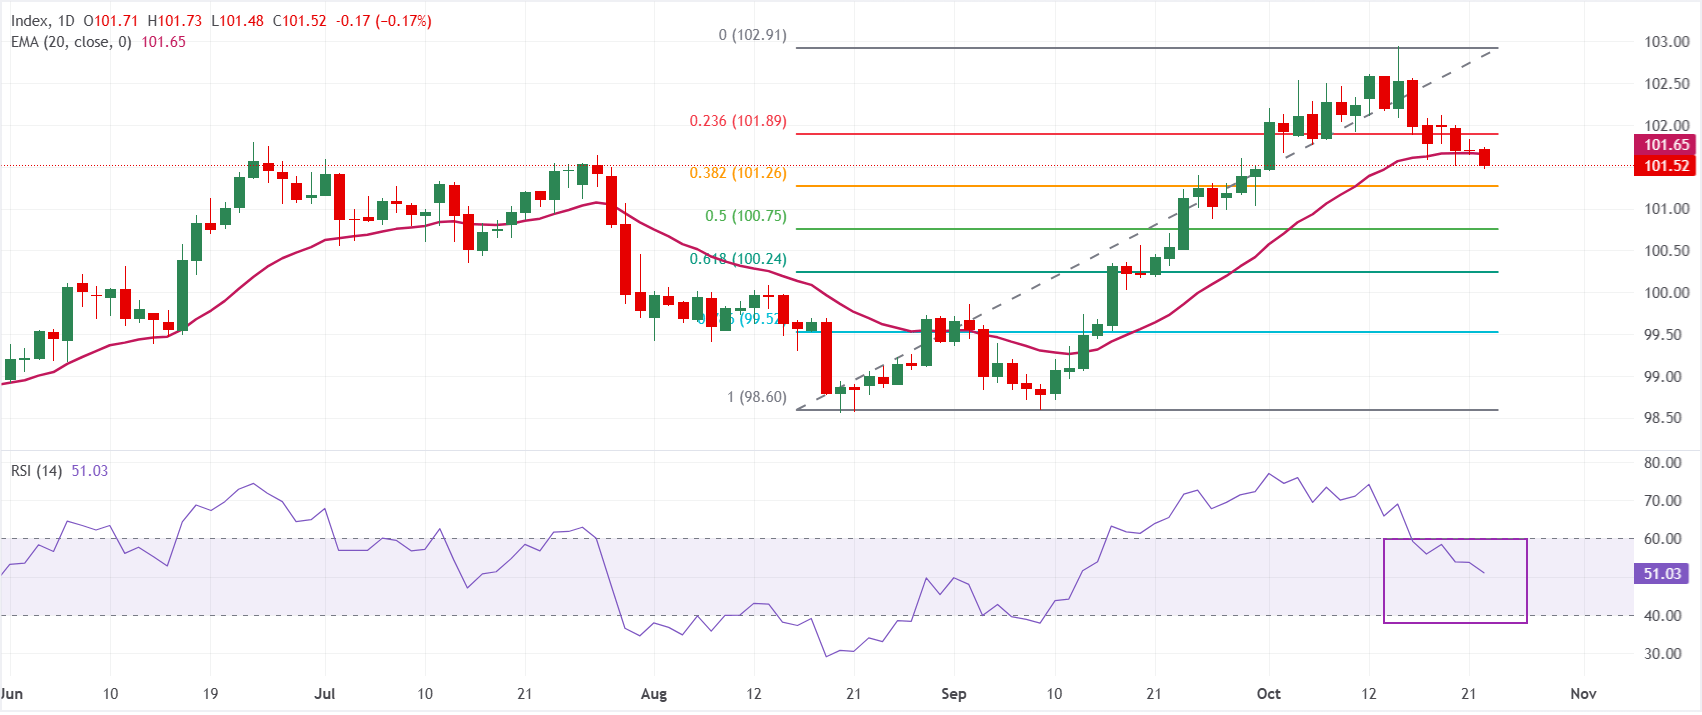
At 101.52 on the daily chart, Dollar Index Spot remains below its 20-day Exponential Moving Average (EMA) of 101.65 but above the 38.2% Fibonacci retracement at 101.26. This positioning points to a neutral near-term outlook and consolidation following the recent rise. With the Relative Strength Index (14) near 51, directional conviction appears to have weakened, leaving neither buyers nor sellers clearly in control.
The 20-day EMA at 101.65 provides the first resistance level, ahead of the 23.6% Fibonacci retracement at 101.89. A sustained move through both would clear a path towards the recent swing high near the 0.0% retracement at 102.91. Below the market, the 38.2% retracement at 101.26 offers initial support, followed by 100.75 and 100.24, corresponding to the 50.0% and 61.8% retracements. A more pronounced decline would bring the 78.6% level at 99.52 into view, followed by the base of the current Fibonacci range near 98.60.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
As the official currency of the United States of America, the US Dollar (USD) also circulates alongside domestic banknotes in a significant number of other countries, serving as their ‘de facto’ currency. Data from 2022 show that it accounts for over 88% of global foreign exchange turnover, equivalent to an average of $6.6 trillion in daily transactions, making it the world’s most actively traded currency. The USD replaced the British Pound as the global reserve currency after the Second World War. Gold backed the US Dollar for most of its history, until the Bretton Woods Agreement in 1971 brought an end to the Gold Standard.
Monetary policy, set by the Federal Reserve (Fed), is the single most influential driver of the US Dollar’s value. Adjusting interest rates is the Fed’s main means of fulfilling its two mandates: maintaining price stability by controlling inflation and promoting full employment. Inflation above the Fed’s 2% target, with prices rising too rapidly, prompts the central bank to increase rates, supporting the USD. Conversely, the Fed may cut interest rates if inflation slips below 2% or the unemployment rate is too high, putting pressure on the Greenback.
When conditions become extreme, the Federal Reserve can print additional Dollars and introduce quantitative easing (QE), substantially expanding the supply of credit to a financial system that has become stalled. This unconventional policy is deployed when credit dries up because banks, fearing that counterparties may default, are unwilling to lend to one another. As a last resort, it is used when interest rate cuts alone are unlikely to deliver the required outcome. During the Great Financial Crisis in 2008, QE was the Fed’s preferred response to the credit crunch. Under the programme, the Fed prints additional Dollars to purchase US government bonds, mainly from financial institutions. The US Dollar generally weakens as a result.
Reversing that process, quantitative tightening (QT) sees the Federal Reserve cease bond purchases from financial institutions and refrain from reinvesting the principal repaid on maturing bonds in further purchases. This is generally supportive of the US Dollar.










The information provided on this website is of a general nature only and does not constitute personal financial advice. Before acting on any information on this website, you should consider the suitability of the information in relation to your objectives, financial situation and needs. Investing in CFDs and FX Margin Contracts carries significant risks and is not suitable for all investors. You may lose more than your initial deposit. You do not own, or have, any interest in the underlying asset. We recommend that you seek independent advice and ensure you fully understand the risks involved before trading. It is important that you read and consider the disclosure document before you acquire any product listed on the website. The information and advertisements offered on this website are not intended for use by any person in any country or jurisdiction where such use would be contrary to local laws and regulations. The Products and Services offered on this website are not intended for residents of the United States, Malaysia and Thailand.
TMGM is authorized and regulated in various jurisdictions.
Trademax Australia Limited, trading as TMGM, is regulated by the Australian Securities and Investments Commission (ASIC), AFSL no. 436416 and is located at Level 28, One International Tower, 100 Barangaroo Avenue, 2000 Sydney, NSW Australia.
Email: [email protected]
Trademax Global Limited, trading as TMGM, is authorized and regulated by the Vanuatu Financial Services Commission (VFSC), registration number 40356 and registered at 1276, Kumul Highway, Port Vila, Vanuatu, Republic of Vanuatu.
Email: [email protected]
Trademax Global Markets (SE) Limited, trading as TMGM, is authorized and regulated by the Financial Services Authority (FSA) of Seychelles, with license number SD224. The company is registered at Office No 13, Providence Estate ABIS Centre, Mahe, Seychelles.
Email: [email protected]
Trademax Global Markets (International) Pty Ltd, trading as TMGM, is authorized and regulated by the Financial Services Commission, Mauritius (FSC) with license no. GB22201012, and registered at 33, Edith Cavell Street C/o IQ EQ Fund Services (Mauritius) Ltd Port Louis, 11324 Mauritius.
Email: [email protected]
Copyright © TMGM. All rights reserved


